Virtual reality
Fully immersive, headset-based worlds for gaming, training, design reviews and social experiences.
Market overview
The metaverse market brings together the hardware, software and services that let people step inside persistent, shared 3D environments. It spans consumer experiences such as immersive gaming and virtual commerce as well as enterprise uses like digital twins, simulation-based training and virtual collaboration.
From USD 179.47 Billion in 2025, the market is projected to reach USD 4,495.56 Billion by 2035, a 38.0% CAGR over 2026–2035. Better devices, faster networks and generative AI are turning immersive technology from an experiment into everyday infrastructure for a growing number of organizations.
Eight technology pillars define how the market creates value across consumer and enterprise use cases.
Fully immersive, headset-based worlds for gaming, training, design reviews and social experiences.
Digital information layered onto the physical world through smartphones, tablets and smart glasses.
Blended experiences where virtual objects respond to real surroundings in real time.
Live virtual replicas of products, factories and cities used to simulate, monitor and optimize operations.
Virtual storefronts, 3D try-ons and digital goods that turn browsing into immersive shopping.
Persistent worlds, social play and creator-built experiences with their own in-game economies.
Devices and software that understand 3D space, so people interact through gaze, gesture and voice.
Shared 3D workspaces for meetings, co-design, remote assistance and team training.
Market forecast
The global metaverse market is projected to expand at a 38.0% CAGR between 2026 and 2035, reaching more than 25 times its 2025 value by the end of the forecast period.
Global metaverse market size
USD Billion, 2025 to 2035
CAGR 38.0% (2026–2035)
| Metric | Period | Value |
|---|---|---|
| Market size | 2025 | USD 179.47 Billion |
| Market size | 2035 | USD 4,495.56 Billion |
| CAGR | 2026–2035 | 38.0% |
2025 · Base year
USD 179.47 Billion
Market size at the start of the outlook.
2026 · Forecast period begins
38.0% CAGR
Compound annual growth rate across 2026–2035.
2035 · Forecast horizon
USD 4,495.56 Billion
Projected market size at the end of the forecast period.
Growth multiple, 2025 to 2035
More than 25x
Calculated from the reported 2025 and 2035 market values.
Market trends
Immersive technology is maturing fast. These trends are redefining how virtual worlds are built, accessed and monetized.
New headsets and smart glasses blend digital content with physical space, moving immersive experiences beyond gaming into everyday work and life.
AI tools that turn text and images into 3D assets, avatars and environments are shrinking production cycles for creators and brands.
Manufacturers, utilities and city planners mirror physical assets in real time to simulate scenarios, anticipate failures and optimize performance.
Brands are launching virtual storefronts, AR try-ons and digital goods that connect immersive engagement directly to sales.
Shared formats such as OpenUSD and glTF make 3D content more portable between engines, platforms and devices.
Streaming high-fidelity scenes from the cloud and the network edge to lightweight devices lowers hardware barriers for users.
Growth drivers
Several forces are compounding at once: hardware is improving, networks are getting faster and organizations are finding practical reasons to invest in immersive technology.
Compound annual growth rate, 2026–2035
Lighter headsets, sharper displays, color passthrough and capable smart glasses are lowering the barrier to immersive experiences.
5G, modern Wi-Fi and edge infrastructure cut latency for real-time 3D, multiplayer worlds and cloud streaming.
Digital twins, immersive training and remote assistance help industrial teams improve safety, speed and decision-making.
Large, engaged communities and user-generated worlds sustain active virtual economies built on in-world purchases and creator tools.
Virtual events, branded worlds and 3D product experiences give marketers new ways to reach digital-native audiences.
Distributed teams are adopting shared virtual spaces for meetings, onboarding and collaborative design.
Market by component
The metaverse value chain runs from the devices people wear to the engines that render worlds and the specialists who deploy them.
The devices and silicon that place people inside immersive worlds.
The engines and platforms that create, run and manage virtual environments.
The expertise that turns immersive technology into business outcomes.
Platform types
People reach the metaverse through different devices, and the worlds they enter are run under different platform models.
PC and browser-based worlds with high-fidelity graphics, creator tools and enterprise collaboration.
The most accessible gateway, powering AR effects, location-based play and on-the-go virtual commerce.
VR, AR and mixed reality devices that deliver the deepest sense of presence for gaming, training and design.
Company-operated platforms where people play, socialize and create inside a managed ecosystem.
Blockchain-based worlds where users can own digital land, assets and identities.
Secure environments built for digital twins, simulation, training and collaboration.
Revenue models
Consumer spending, enterprise software and brand budgets each feed different parts of the market.
Skins, wearables, upgrades and digital collectibles sold inside virtual worlds and games.
Headsets, smart glasses, controllers and accessories sold to consumers and enterprises.
Recurring access to content libraries, premium features, fitness programs and social experiences.
Engines, platforms and digital twin software licensed per seat, per project or by usage.
Sponsored worlds, in-world placements, virtual concerts and immersive product launches.
Commissions on creator marketplaces, virtual property and digital asset trading.
Industry applications
From entertainment to the factory floor, organizations are using virtual worlds, digital twins and spatial interfaces to engage customers and run operations.
Persistent worlds, VR titles and live social experiences with player-driven economies.
Virtual storefronts, AR try-ons and digital fashion that let shoppers explore products before they buy.
Immersive lessons and hands-on simulations for learning complex or high-risk skills safely.
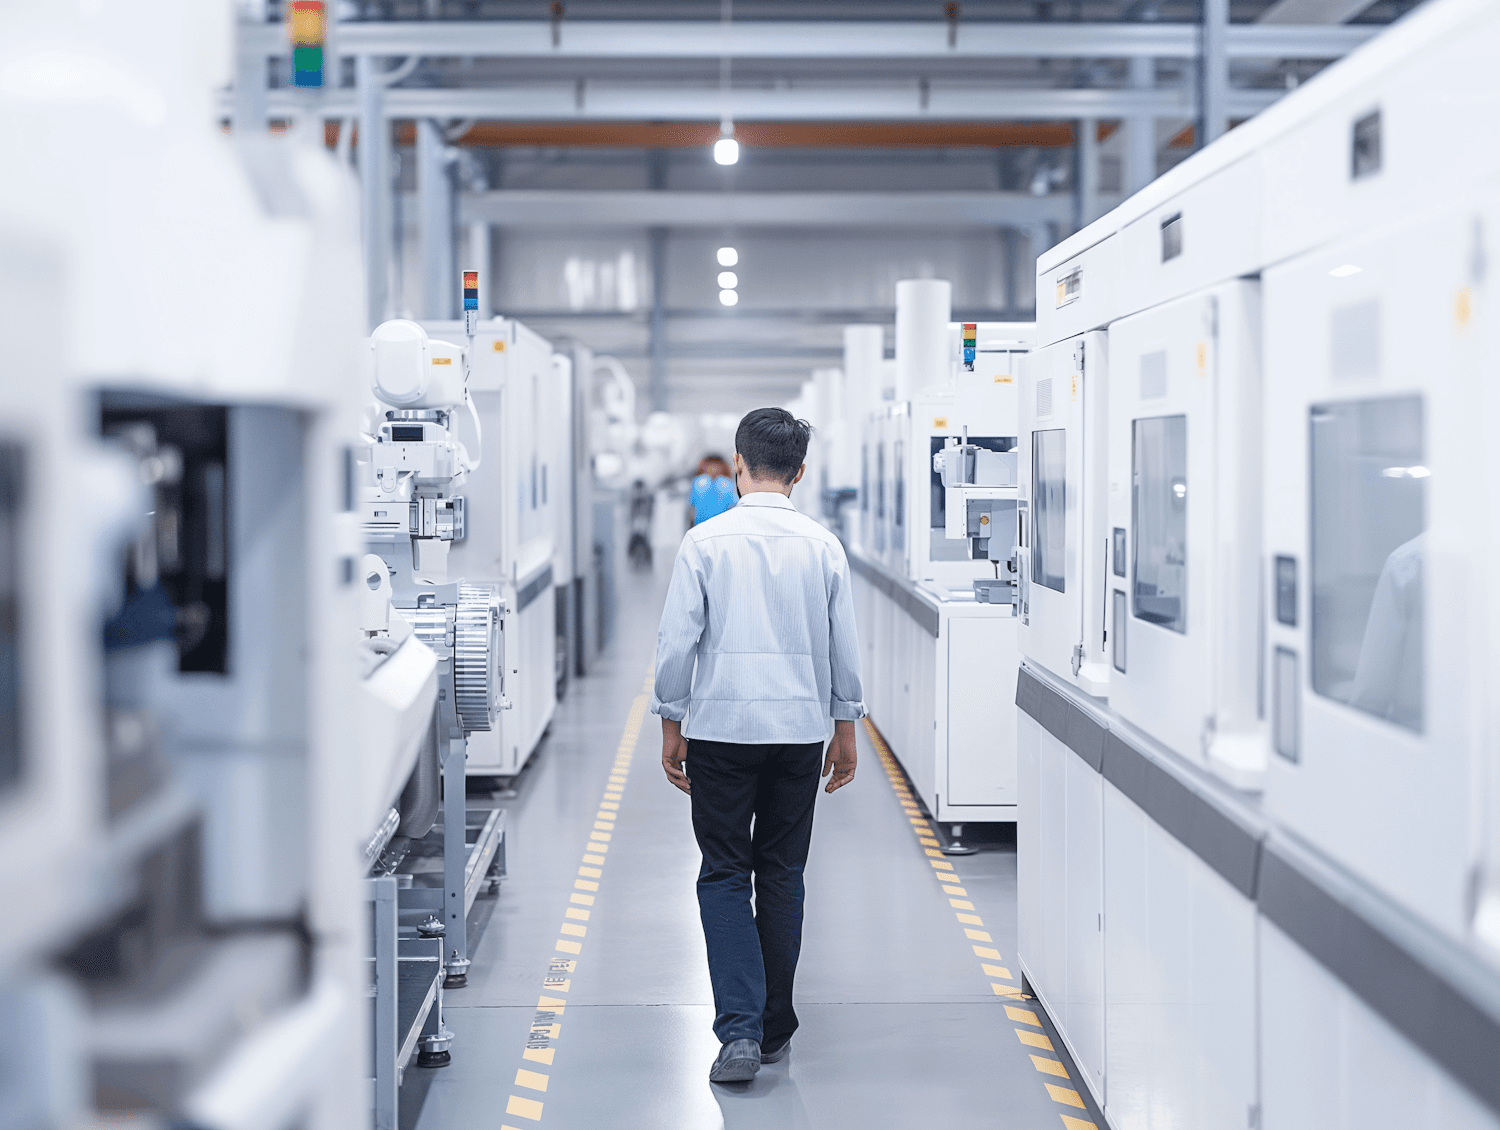
Virtual replicas of plants and production lines for planning, monitoring and predictive maintenance.
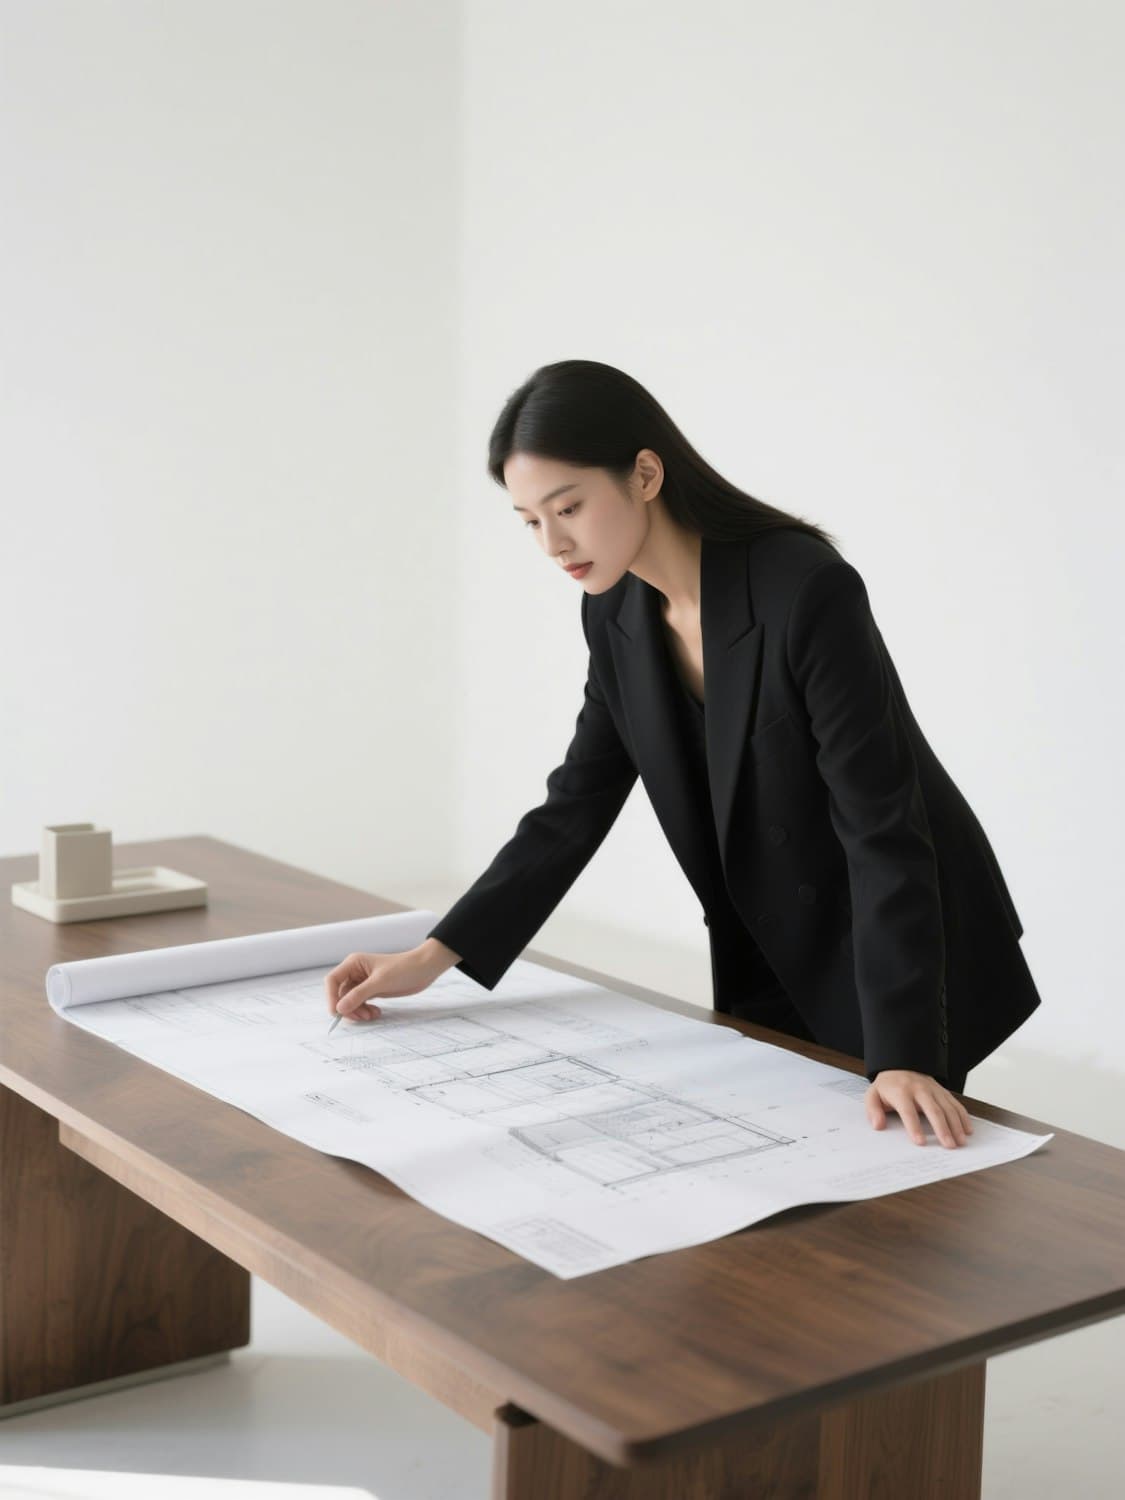
Virtual tours, 3D design reviews and digital property that speed up planning and sales.
Virtual concerts, product launches and branded worlds that reach audiences anywhere.
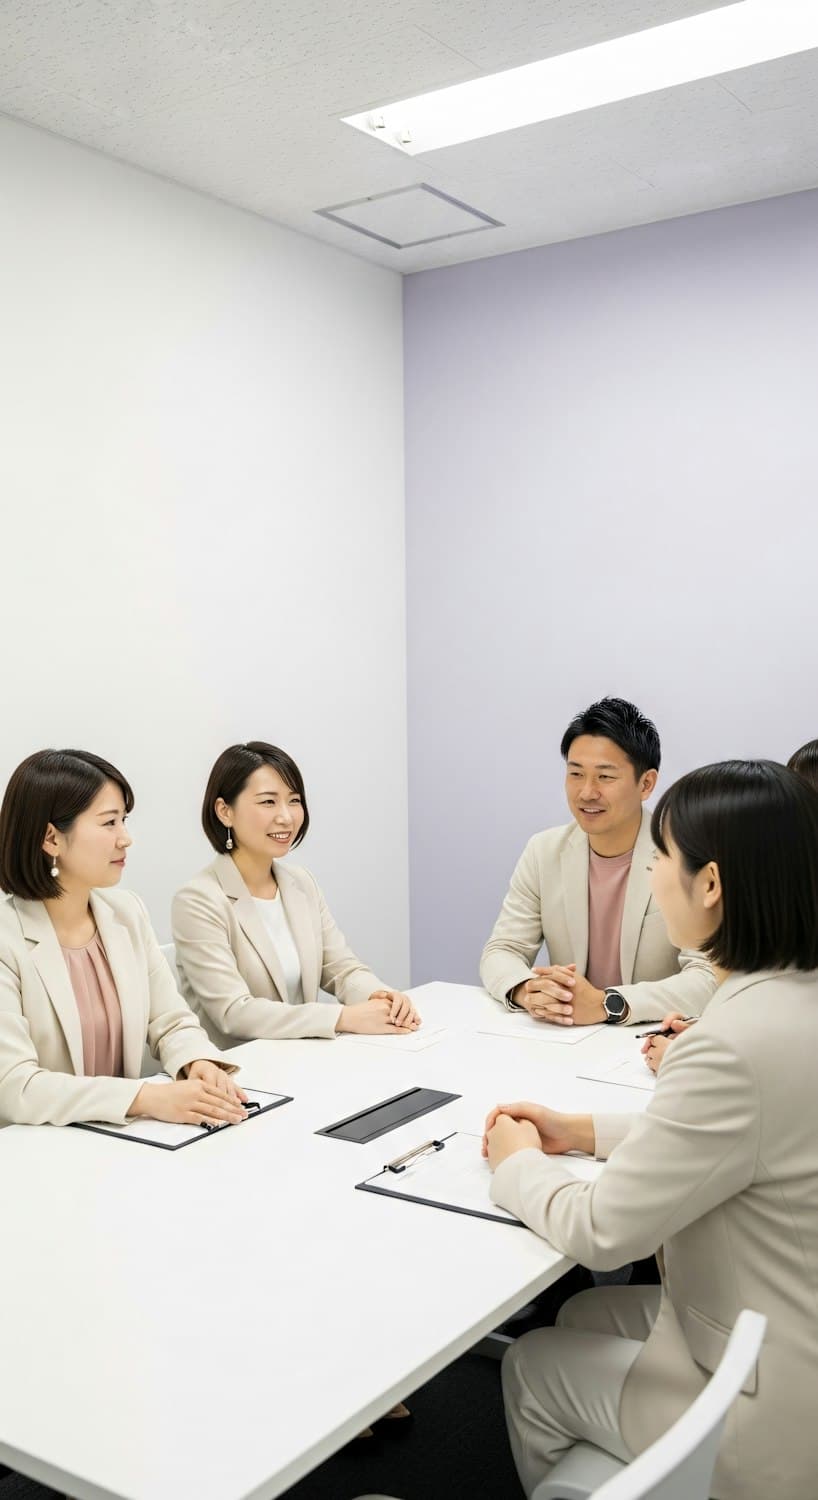
Shared virtual offices, meetings and co-design sessions for distributed teams.
Healthcare and life sciences
Surgical planning, therapy and medical training.
Automotive
Virtual prototyping and immersive showrooms.
Aerospace and defense
Simulation-based training and mission rehearsal.
Banking and financial services
Virtual branches and immersive customer engagement.
Travel and tourism
Virtual destination previews and cultural experiences.
Regional insights
Adoption patterns differ by region, driven by each market's industrial base, consumer habits and digital policy.
Platforms, devices and venture capital
Home to many of the platform owners, engine makers and device brands behind the metaverse, North America pairs a deep developer ecosystem with early enterprise adoption across gaming, retail and industrial training.
Industrial twins and trusted platforms
European adoption is anchored in industry. Automotive, manufacturing and engineering companies use digital twins and virtual prototyping, while privacy and data regulation shape how immersive platforms are built.
Mobile-first audiences and device supply chains
A mobile-first, gaming-centric consumer base, extensive electronics manufacturing and smart city initiatives make Asia Pacific a dynamic hub for metaverse hardware, content and commerce.
Mobile-led adoption and creator communities
Expanding mobile connectivity and vibrant gaming communities are driving mobile-led adoption, with brands using immersive experiences to reach young, digital-native audiences.
National digital agendas and smart cities
Ambitious national digital transformation programs, smart city megaprojects and investment in tourism and entertainment are creating demand for digital twins and immersive experiences.
Key players
Device makers, platform owners, engine providers and chip designers are investing across the value chain, from the silicon inside headsets to the worlds people visit.
Quest headsets and social virtual worlds
Devices and platforms
Cloud, AI and digital twin services for enterprises
Enterprise platforms
Vision Pro and the visionOS spatial computing platform
Spatial computing
Omniverse platform and GPUs for simulation and digital twins
Simulation and silicon
Android XR platform and ARCore augmented reality
XR platforms
Unreal Engine real-time 3D and Fortnite experiences
Engines and gaming
User-generated virtual worlds and a creator economy
Virtual worlds
Real-time 3D development platform across devices
Engines
Gaming, social and digital content ecosystems
Gaming and social
PlayStation VR2 and immersive entertainment
Devices and content
Snapdragon XR chipsets for headsets and smart glasses
Silicon
PICO virtual and mixed reality headsets
Devices
FAQs
Quick answers on market size, growth, technologies and how to access the full report.
The global metaverse market was valued at USD 179.47 Billion in 2025.
The metaverse market is projected to reach USD 4,495.56 Billion by 2035.
The market is expected to grow at a CAGR of 38.0% over the forecast period from 2026 to 2035.
The market spans virtual reality (VR), augmented reality (AR), mixed reality (MR), digital twins, virtual commerce, immersive gaming, spatial computing and virtual collaboration, supported by hardware, software and services.
Key drivers include more capable and affordable XR devices, faster networks and edge computing, enterprise demand for digital twins and immersive training, gaming and the creator economy, brand investment in immersive engagement and the shift to remote and hybrid work.
Adoption spans gaming and entertainment, retail and e-commerce, education and training, manufacturing, real estate and architecture, media and events, workplace collaboration, healthcare, automotive, aerospace and defense, financial services and travel.
Revenue comes from virtual goods and in-world purchases, hardware sales, subscriptions, enterprise software licensing, advertising and branded experiences, and marketplace and transaction fees.
Prominent companies include Meta Platforms, Microsoft, Apple, NVIDIA, Alphabet (Google), Epic Games, Roblox Corporation, Unity Technologies, Tencent, Sony Group, Qualcomm and ByteDance.
Open the full market report from Market Research Future to explore the complete study, or request a free sample to review it first.
Future outlook
By 2035, the metaverse market is projected to reach USD 4,495.56 Billion. The next decade will be defined by convergence, as AI, spatial computing, digital twins and real-time 3D combine into persistent digital layers for how people work, learn, shop and play.
Horizon 1
Enterprise digital twins, immersive training and gaming platforms prove their value and scale across industries.
Horizon 2
Generative AI, lightweight AR glasses and cloud rendering make immersive experiences faster to build and easier to access.
Horizon 3, by 2035
Persistent, interoperable virtual environments become an everyday layer for commerce, collaboration and entertainment.
Projected market size by 2035
USD 4,495.56 Billion
Metaverse market report
Go beyond the headline numbers with detailed analysis of the segments, regions and companies shaping a market projected to reach USD 4,495.56 Billion by 2035.